
Australian firms can miss fringe benefit tax (FBT) when employee benefits sit outside payroll or aren’t supported by clear records. Most fringe benefit tax work fails on identification and evidence rather than arithmetic, not on the calculation itself.
The year catches people out. It closes on 31 March, not 30 June, and the return and payment generally fall due 21 May, or 25 June for electronically lodged agent returns where the client was on the agent’s FBT list by 21 May.
What is fringe benefit tax in Australia?
FBT is a tax the employer pays on non-cash benefits handed to staff or their associates, a spouse being the usual example. The ATO administers it separately from income tax and GST. The first control is coverage. Sweep payroll, expenses and the other ledgers, because the benefit coded to a single account is the one you miss.
Common benefit categories include:
| Category | Examples or review focus |
|---|---|
| Car | Check the benefit and supporting logbook records |
| Expense payment | Review payments and reimbursements |
| Entertainment | Identify benefits recorded outside payroll |
| Loan or debt waiver | Check employee-related arrangements |
| Housing or living away from home | Review supporting records and benefit classification |
| Residual | Capture benefits that do not fit another category |
A residual fringe benefit is the catch-all, and it is where the coding problems show up. A gym membership, a professional subscription paid on an employee’s behalf, private use of employer-owned property: none of these arrive labelled as a benefit, so the file only catches them if someone reads the ledger looking for the employee’s name attached to a cost.
The ATO’s employer guidance on fringe benefits tax is a useful starting point for checking classifications, though the table above is a review prompt rather than a complete statement of the rules.
How does the fringe benefit tax year affect key dates?
FBT runs on its own calendar, which never lines up with the income tax year the client is already tracking. The 25 June agent date applies to electronic lodgement only, needs the client on the agent’s FBT list by 21 May, and payment falls due the same day as lodgement. A paper return lodged by an agent is still due 21 May.
Where there is no liability at all, the usual path for an employer registered for FBT is an FBT Notice of Non-Lodgment by 21 May rather than a nil return. Lodging either starts the standard amendment period, so the year is closed out; doing neither leaves it open indefinitely.
How do fringe benefit tax gross-up rates work?
The FBT rate is 47%, applied to the grossed-up taxable value. Which gross-up rate you use turns on whether a GST credit was available.
| Calculation detail | Type 1 | Type 2 |
|---|---|---|
| When to use | Employer can claim a GST credit | No GST credit is available |
| Gross-up rate | 2.0802 | 1.8868 |
| FBT rate applied to grossed-up value | 47% | 47% |
FBT payable = (taxable value × gross-up rate) × 47%.
For example, a car benefit with a taxable value of $10,000 that is fully GST-creditable grosses up to $20,802. Applying the 47% FBT rate produces FBT of about $9,777. Keep the taxable value, GST-credit treatment and calculation together in the workpaper so a reviewer can trace each step.
The ATO’s FBT rates and thresholds confirm which rates apply to the return period.
RFBA meaning and when fringe benefit tax reporting starts
RFBA means reportable fringe benefits amount. The trigger is the total taxable value of reportable benefits across the year exceeding $2,000, tested before any grossing up. What you then report is that taxable value grossed up at the Type 2 rate of 1.8868, regardless of whether the benefits themselves were Type 1 or Type 2, so the smallest reportable amount is $3,773.
An RFBA is not taxed again. However, it counts in income tests, including the Medicare levy surcharge, HELP repayments and child support. Salaried superannuation contributions are not fringe benefits and do not create an RFBA.
How does fringe benefits tax salary sacrifice work?
Salary sacrifice needs its own check, because a benefit provided in place of salary can still carry an FBT liability. The minor benefits exemption does not apply, since salary-sacrificed benefits are regular by design; it covers only infrequent or irregular benefits under $300.
Check the arrangement and its records before applying an exemption or calculating an RFBA. BlueCrest’s payroll management support covers payroll processing and STP support for Australian accounting firms.
How does fringe benefit tax connect to payroll tax?
Payroll tax is a state and territory tax with its own rules in each jurisdiction. Most jurisdictions include the grossed-up value of fringe benefits in taxable wages, so one set of FBT workpapers feeds both returns. Confirm the treatment with the relevant state or territory revenue office.
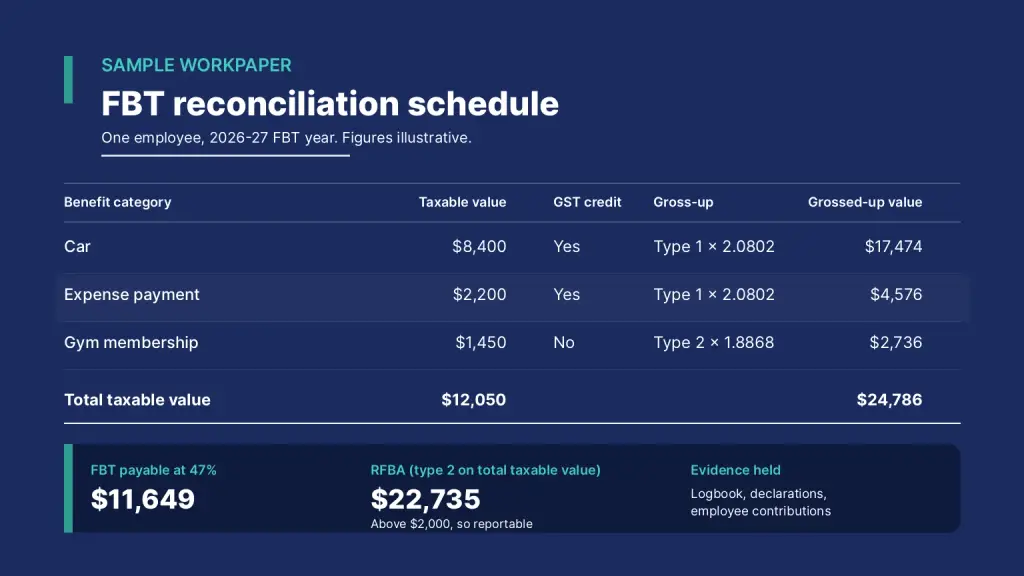
A review-ready file lets another practitioner trace each benefit from source document to calculation to return. Reconcile across payroll and expense records, then record why each item is included, excluded or reduced.
At minimum, retain and cross-check:
- Logbooks and the records used to determine taxable values.
- Declarations and employee contributions.
- Evidence supporting any reduced taxable value.
- A schedule linking benefit categories to the relevant calculations and reporting.
- The basis for any non-lodgment or nil-return conclusion.
Where the data needs cleanup first, BlueCrest’s bookkeeping services handle reconciliations and ledger preparation, and tax preparation support helps organise draft workpapers for your own review and lodgement.
How should accounting teams prepare for fringe benefit tax year-end?
The work is a sequence. Pin the period first, because everything downstream depends on which twelve months you are testing. Most rework happens where the line from client records to return breaks.
Work through it in this order:
- Confirm the FBT year and lodgement date.
- Scan payroll, expense and other ledgers for benefits.
- Classify each item, including residuals.
- Settle the GST-credit question before picking a gross-up rate; the wrong one quietly overstates or understates the liability.
- Check RFBA separately against the $2,000 threshold.
- Tie evidence, calculations and return figures together.
- Confirm the payroll tax treatment with the state revenue office.
This guide provides general information for Australian accounting practitioners. Apply the legislation and current ATO and state revenue office requirements to the facts of each employer’s circumstances.
Last reviewed for the 2026–27 FBT year.